- The New Zealand economy exceeded expectations to squeeze out not just 0.1%, but 0.2% growth over the June quarter! Construction played a major part, but consumer weakness was evident in sectors reliant on discretionary spending, such as retail.
- The US Federal Reserve hiked interest rates for the first time in three years. US bond yields initially eased as a result. One additional hike in 2026 was signalled. But like in NZ, markets are pricing more aggressively.
- July was the first month where overseas tourist arrivals exceeded pre-COVID levels. July 2026 visitor arrivals were 100.4% of those seen in July 2019, and we’re optimistic that a bumper summer season will keep that momentum going. We are so back, baby!
The economy expanded by 0.2% over the June quarter. That’s 1.7% annualised growth and a 2.6% increase compared with the June quarter of 2025. Those figures came in a touch above market consensus and our own forecast of 0.1%, 1.6% and 2.2% across the three measures respectively.
Strength was relatively broad-based. Of the 9 (out of 16) industries that grew, construction takes the cake. Transport took a big hit, which isn't surprising given its direct exposure to the oil shock. Arts and recreation, as well as retail and accommodation also experienced contractions. Likely a symptom of a weak consumer.
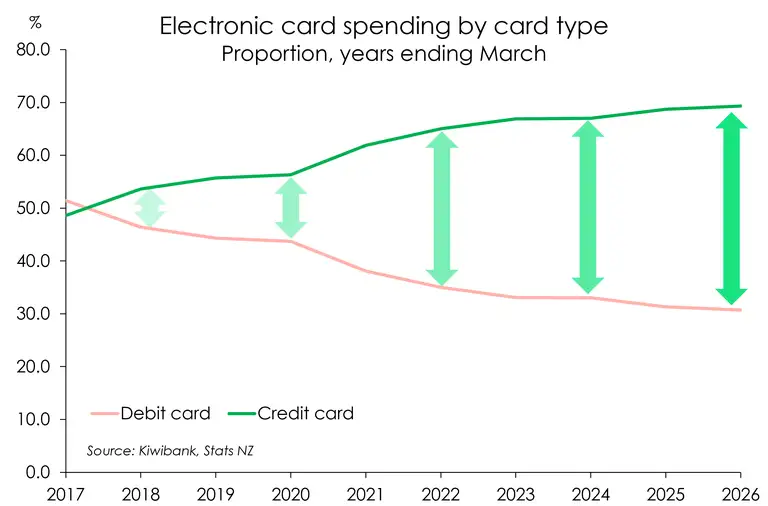
Growth in consumer spending slowed right down from 0.6% in the March quarter, to 0.1% in the June quarter. Spending on services and non-durable goods were flat and negative respectively. Clearly, many Kiwi households tightened their purse strings amidst increasingly painful petrol station visits. Private consumption (which adds charity spending in alongside household spending) was down overall. Government consumption was also down, led by a sizeable drop in central government spending.
We have seen plenty of commentary that the economic growth observed over the June quarter should lead the Reserve Bank to hike in October rather than waiting for December. We think this kind of call is premature. Yes, the economy grew above the market’s and the Reserve Bank’s expectations despite a very challenging global backdrop.
But when the economy is still in embers, now is not the time to be dousing it with water. The labour market is still languishing, and consumers are still cautious. For more in-depth analysis of last week’s economic growth data, check out our take here.
The US Federal Reserve Bank hiked for first time in 3 years, taking the target range to 3.75-4%, up 25 basis points. This move was intended to quell stubbornly high inflation, aiming to get it back to the 2% target faster. The Fed communicated that the US economy was doing well. Their updated forecasts suggest they are not overly worried about a worsening inflation outlook. US bond yields eased and the New Zealand dollar fell in response. One additional 25 basis point hike was signalled, but markets are pricing much more hawkishly.
The divergence between what the Fed is signalling for future rates and what the market is expecting is a familiar story. It echoes what’s happened in New Zealand, with markets pricing in more rate hikes than the Reserve Bank is signalling. This is driven by traders thinking there is a greater likelihood of energy prices remaining higher for longer. Which would lead to higher inflation. And if that were to happen, it would force the hands of central banks to hike interest rates even higher. We acknowledge the upside inflation risk, but think the market is overcooking it.
Last week was a treasure trove of data. The gem that shone the brightest was the tourism numbers. July 2026 marked the first time that overseas tourist arrivals exceeded the numbers for the same month of 2019. Tourists were likely enjoying our dramatic scenery, warm hospitality, and cheap currency. We expect this momentum to continue building as we near the peak summer tourism season.
Financial Markets
The comments below were provided by Kiwibank traders. Trader comments may not reflect the view of the research team.
In Markets - Policy paths the key
Last week, markets steadied themselves somewhat after the ructions in rates the week prior with central banks and data back in focus. Internationally we had the US Federal Reserve decision and accompanying projection materials, including the ‘dot-plot’, the Bank of England, and the Bank of Japan, while locally we had Q2 GDP data followed by some CPI partials in the form of the selected price indices series. We also saw further hawkish commentary from the RBA, this time to the Australian House of Representatives Standing Committee on Economics, while the RBNZ announced the departure of MPC member Karen Silk. For the week, our implied cash rate curve looked to finish marginally lower, year-end priced at around 3.10% against 3.13% the prior week, and year-ahead at around 3.78% against 3.84% previously. Further out, our rates curve was lower and flatter, with the 2-year IRS seen at 3.98% (-7bp week on week), 5-year IRS 4.33% (-9bp), and 10-year IRS 4.64% (-10bp).
Rates markets remained on edge ahead of the Fed meeting, with inflation concerns still prominent and driving nervous trade ahead of the FOMC. The meeting was also seen as a test of the committee and in particular whether Fed Chair Warsh would look to restart the tightening cycle in an effort to manage sticky core inflation. The FOMC voted unanimously to raise the benchmark Fed Funds target range by 25-points to 3.75%-4.00% in the first hike since mid-2023. The statement was succinct, stating that “policy action would support a timelier return to the Committee's 2% goal”, finishing with the firm sentence that “the Committee will deliver price stability”. Following the release, Warsh reiterated his previous comments in Jackson Hole that he would be hard pressed to describe broad financial conditions as restrictive, noting that recently a broad range of data including labour market data, would indicate that the economy had strengthened. The market also looked to the ‘dot-plot’ – the simple plot of FOMC participants’ assessments of appropriate monetary policy going forward, with the plots leaning on the side of likely tighter conditions then previous for 2026 and 2027. Prior to release, Treasuries and Fed Funds futures had been trading lower in yield terms, with reaction post release being a swift reversal, particularly at the front of the curve, resulting in a flattening. Fed Funds futures one year ahead expectations reversed early gains of around 7bp to finish 10bp lower. The 17-point turn-around on the session was a result of the firmer implied forward conditions through the dot-plot. Looking forward, this may start to see the inflation risk premium, one of the many factors that had looked to weigh on US rates of late, potentially dialled back a touch.
Fed hike day also saw the release of NZ Q2 GDP data which printed at +0.2% and +2.6% y/y. Market consensus has been for a +0.1% for the quarter while the recent RBNZ MPS had a flat result in the projections, though their GDPNow predictor model had indicated around 0.2% the week of their MPS release. The firmer result and prior period upward revisions did see 2027 implied cash rates lift, with the front of our curve also adding some tentative early losses. This lead to a pivot around the 5-year area as the back of the curve finished a point lower in yield. Overall, the feel was that the print, while above expectation, was not sufficiently strong enough to add further to already steep market pricing which is already tracking a number of tightenings ahead of the recent MPS projections. Local data continued Friday with the release of Statistics NZ Selected Price Indices with this newer data series part of Statistics NZ’s work on providing more timely inflation data, covering around 44% of the CPI basket. The release was viewed as broadly neutral to softer by the market, with yields and currency lower after the release. Further blunt talk on inflation from the RBA, the sort which would normally see higher yields in Australia and NZ, only momentarily pausing the rally. Our timezone also had the BoJ move on rates, lifting the overnight rate to 1.25% in a 7-2 decision. The move itself had been priced and expected, though the split decision and softer post-meeting tone disappointed markets that had been expecting a clearer indication around the tightening path.
Looking forward, the increasingly complex geopolitical environment on many fronts has seen markets start to take a stronger stance on inflation, becoming less patient with the transitory arguments and showing concern at persistently elevated headline and core inflation. Our curve has not been immune despite the very recent update delivered in the MPS, with the short-curve bringing forward near-term priced tightening probability to the October meeting, while year-end once again pricing above 3% finishing the week at 3.10%. The 2027 dates don’t fare any better either, with implied Q1, Q2, and Q3 OCR averages seen at 3.23%, 3.56%, and 3.75%, some 27, 49, and 63-points above the projections delivered on 2 September. As noted last week, recent decision making and meeting records from the RBNZ would indicate a fair degree weight is also applied to the parts of the remit dealing with avoiding unnecessary instability in output and employment, and the current oil and rates shock may just feed a bit more into their thinking in these areas. Noting that they appear to remain a little more cautious as to the underlying demand in the economy as evidenced by the last two MPS’s, in contrast to the outlooks of the Fed and the RBA on their respective economies. While the firmer GDP print and revisions may have seen some of the assumed output gap pared back, the current assumed gap is likely to remain near-term, and hence may not materially alter their view. With the seemingly neutral SPI likely providing some relief. All up, this may mean that the RBNZ may continue with their measured approach despite market pricing – the what they will do against what the market believes they should do argument. This may see the front of the swap curve, within reason, supported while it remains stretched against their forecast cash rate path, leaving the longer end to more closely follow international developments, potentially a re-steepening of the curve after the recent flattening witnessed. Here too, the different stances of the respective central banks may continue to play out in currency markets, most notably NZDAUD as the RBA looks to be less patient on persistent inflation. Of note is that Anna Breman will deliver an economic update at a business lunch on Tuesday, though the blurb on this notes that no new insights beyond those contained in the September MPS will be shared, though I guess there will always be a Q&A that may elicit a headline. Graham Hughes – Trader, Financial Markets
In FX – The Kiwi’s interest rate problem
The US dollar starts the week on the front foot after a more hawkish Federal Reserve reinforced the prospect of higher-for-longer interest rates, helping lift the US Dollar Index back above 100 and keeping NZD/USD pinned near the lower end of its recent range. While the Kiwi found late week support above the 57-cent area, the broader trend remains one of subdued momentum as higher US yields, resilient US economic data and ongoing geopolitical uncertainty continue to support demand for the greenback. Across the Tasman, the Australian dollar has also found support from increasingly firm rhetoric from the Reserve Bank of Australia, with policymakers continuing to highlight upside inflation risks and the prospect that policy may need to remain restrictive for longer than markets had previously anticipated.
Closer to home, attention is increasingly turning to NZD/AUD after the cross traded to a fresh 16-year low of 0.8017 last week. We will look to explore this theme further in this week's fresh drop of our quarterly FX Tactical, but as a bit of sneak peak, the balance of risk is now skewing to the downside. Interest rate markets continue to favour Australia, with one-year forward pricing implying a sizeable premium for Australian cash rates over New Zealand, and there is scope for that differential to widen further if markets move closer to the respective policy paths signalled by the RBA and RBNZ. Technically, the break around 0.8140 to fresh multi-decade lows is also significant, suggesting the market is continuing to reward Australia's relatively stronger inflation backdrop and more hawkish policy outlook. Targeting specific levels lower at this point is a bit of a blue-sky challenge with little technical support existing well into the 70’s. The combination of policy divergence, relative yield support and a resilient Australian economy suggest NZD/AUD will remain an important cross for customers to watch in the weeks ahead. Hamish Wilkinson – Senior Dealer, Financial Markets.
The Week's Key Events
- It’s a very quiet week ahead after last week being full to the brim with economic data and events.
- Aussie labour market data is out, as is American housing data.
- Other than that, sit back, relax and enjoy the week!
All content is general commentary, research and information only and isn’t financial or investment advice. This information doesn’t take into account your objectives, financial situation or needs, and its contents shouldn’t be relied on or used as a basis for entering into any products described in it. The views expressed are those of the authors and are based on information reasonably believed but not warranted to be or remain correct. Any views or information, while given in good faith, aren’t necessarily the views of Kiwibank Limited and are given with an express disclaimer of responsibility. Except where contrary to law, Kiwibank and its related entities aren’t liable for the information and no right of action shall arise or can be taken against any of the authors, Kiwibank Limited or its employees either directly or indirectly as a result of any views expressed from this information.