- With inflation data out this week, we expect a modest improvement from the June quarter. But it’s December that’s ringing our alarm bells. Just go to a petrol station and find out why…
- Australia had a surprise rise in their unemployment rate, reducing the likelihood of another RBA hike. But the discount on the Kiwi dollar still stands and supports more Aussie tourists to summer this side of the ditch.
- It’s a similar story in the US of A. The implied probability of a rate hike there is zilch, despite a move higher in core inflation.
Domestically we have inflation data coming out later this week. Our inflation prediction is at the high end of the spectrum for the September quarter. We’re expecting it to come out at 4%, just narrowly lower than the June quarter. But we’re quietly hoping we’re wrong. A 3.8% would have us jumping for joy (3.8% was our call for the September quarter back in July).
The key things we are looking for, beyond the headline rate, will be the source: tradable (imported prices) vs non-tradable (domestic prices). At this stage we’re still expecting the majority of this inflation hit to be coming from offshore. And the Selected Price Indices (SPI) out last week support that expectation. Petrol and diesel were actually lower than the June quarter, with little else increasing enough to raise alarm bells. But we are wary.
We’ve been put on notice by businesses consistently reporting, through the QSBO for example, an intention to raise prices. The margin squeeze on many businesses is real and not easing any time soon. So, we see the risk of a spanner in the works. But we’re more worried about the December quarter, seeing how petrol prices have reached record levels right now. I’m sure we all collectively winced the last time we had to fuel up.
The RBNZ is wary of non-petrol price rises too. They’re worried about prices increasing on other goods and services because of the petrol and diesel prices… the second-round effects. We will keep a sharp eye out for this also, along with measures of core inflation. This is likely to shift the needle on the possibility of an October rate hike over a December one, more than anything else we could look at.
Australia had a shock to contend with last week. Labour market data across the Tasman showed their unemployment rate reaching a 5-year high (highest since 2021) of 4.7%. The move was mostly driven by a decrease in the size of their labour force rather than the meteoric rise in the number of unemployed Aussies. The odds of a hold at the Reserve Bank of Australia’s November meeting jumped to 90% as a result.
Now, you might be looking at that 4.7% figure and thinking… wow, if only our unemployment rate was that low! But alas, the Aussies don’t know pain and they’re a little spooked. They haven’t had a technical recession since 2020, and even then, it only lasted two quarters! They’ve forgotten what it feels like.
But really, that works for us, because our currency has still been anchored below 82c on the Aussie dollar for half a year. Despite a pop higher last week, we’re still likely to get some Aussies coming over for a holiday this summer, feeding our economy, reducing our unemployment rate…
The US Federal reserve hiked interest rates at their September meeting, and now, US inflation came in hotter than expected. Core inflation crept up to 2.6% with headline inflation at 3.7%. Despite this, the market is unconvinced that the Fed will hike again at their October meeting. An interest rate move is currently priced at near 0% probability according to Fed funds futures. The meeting is happening right before the US midterm election (not their general election but still...) Does this sound familiar?
Our market remains doggedly convinced that a rate hike in NZ is a foregone conclusion, with the upcoming RBNZ October meeting fully priced in. We’re less convinced.
Financial Markets
The comments below were provided by Kiwibank traders. Trader comments may not reflect the view of the research team.
In Markets – Sentiment shifts evident in markets
Data, debt, European unrest, Central Bank speak, and AI and technology sector jitters drove markets this week ahead of our own Friday data dump. Tier-1 inflation and employment data were released across several key markets. These were accompanied by commentary from a number of US Federal Reserve speakers, remarks from the RBNZ Chief Economist, and the release of the minutes from the latest RBA meeting. Friday concluded with a flurry of domestic data, including manufacturing sector activity and the Selected Price Indices, a series that captures more than 40% of CPI inputs. The result was generally lower and flatter yield curves except for NZ, with this week’s CPI now squarely in focus. For the week, our market mostly followed international developments though at a somewhat measured degree, before weakening sharply on Friday after domestic data saw the market increase the odds for a tightening from the RBNZ. The year-end implied OCR lifted to 3.14% from around 3.08%, year-ahead OCR to 3.86% from 3.83%, while Interest Rate Swaps saw the 2-year close at 4.07% (+5bp week on week), 5-year at 4.38% (-1bp) and 10-year at 4.69% (-7bp).
The focus for US markets over the week was key inflation data in the form of CPI and then PPI, alongside a number of Fed speakers. Ahead of the data, Fed-speak typically landed with a more patient tone, with several Federal Open Market Committee (FOMC) voters pointing to still anchored inflation expectations, a measured pace to any tightening or not seeing any current urgency to move. In the background there also remained some ongoing nervousness in the AI and technology sectors as well as some lingering concerns around Europe, leaving US bond yields to edge lower.
The extent of the sentiment shift became evident following the US CPI release. Both headline and core inflation printed firmer than expected at 3.7% y/y and 2.6% y/y respectively. The initial market reaction was a sharp sell-off, with US 10-year Treasury yields briefly pushing into the mid-5.30% range and Fed Funds futures one year forward falling by around 15bp. However, this move was quickly reversed as the higher-rate backdrop weighed heavily on equities, particularly technology stocks. US bonds finished firmer on the day, with 10-year at around 5.19%. US rates continued the rally after hours in the Asian and European sessions, as stock losses continued to mount, adding a degree of safe-haven, risk-off flow to Treasuries. The following session further emphasised this shift as dataflow again emphasised price pressures with the PPI, like the CPI the day prior, printing well above expectation, with firm retail sales and a stronger regional manufacturing survey adding to the string of recent strong data. However, US rate markets continued to shrug this off, remaining supported by ongoing AI and equity market concerns. Market pricing continuing to assign only around a 20% probability to an October Fed hike. With their bond curve lower and flatter over the week, with their 2-year bonds unchanged over our week while the 10-year finished our Friday marked at 5.09%, down 17bp – a robust performance given the dataflow.
Australian data also provided direction over the week, pulling the market in both directions, with first the release of the minutes from the last RBA meeting then employment data later in the week. Following the seemingly more balanced RBA post-decision press conference after the last move, there had been some speculation that the minutes could reflect this, though upon release this was clearly not the case, with the headlines and the minutes themselves indicating continued concern around prices. This prompted an initial bout of selling in rates markets, however this stalled and then reversed as by now the market was eyeing a continued slide in local business confidence and a continued rally in US rates through the Asian session. Australian employment data on Thursday proved a counter to the minutes release earlier in the week, with a outsized downside miss to the monthly employment change, and a higher headline unemployment rate of 4.7% which was likely spared a worse print by a decline in the participation rate. Australian three- and ten-year bond futures rallying by double-digits in response with their implied cash rate path also moving sharply lower with their curve now pricing another hike as a chance, not a certainty, while tentatively trying to price the chance of an ease post a mid-2027 cash rate peak.
For our market, the data flow arrived on Friday, while the RBNZ Chief Economist made the headlines the day before with some comments noting that the next OCR decision was wide open and reiterating that the direction of the OCR was most likely up. While these headlines were viewed as a touch more hawkish than we have been accustomed to from the RBNZ of late, the dataflow on Friday was what spurred a strong repricing along our curve. A strengthening manufacturing PMI followed by the SPI that really didn’t provide any sign of broad-based weakening in price pressures was enough to spur a rates sell-off lead by the front end of the curve. The data flow following on from the QSBO the prior week not proving any counter to the markets desire to pull forward, and add to the priced tightening path, with the implied curve moving to price the likelihood of an October move in the mid-80%’s, with December now pricing over a half-chance of one more. The Friday selloff also saw some of the previously discussed technical formations in the short-dated forward start IRS market retrace to support, as the curve traded higher at the front on the higher near-term rates view. The current sentiment perhaps leaning towards the market requiring a larger downside miss to the current survey estimates of CPI of +0.8% q/q and 3.8% y/y and no signs of pass-through price pressures to materially shift its view. This sentiment may provide for some keen risk-reward type trades for those who perhaps view the upcoming as less certain than priced. Graham Hughes – Trader, Financial Markets
In FX – Kiwi finds its wings, but CPI holds the key
The Kiwi enjoyed a much better week, with NZD/USD gaining 1.15% to 0.5652 and topping the G10 leaderboard, helped by a broadly softer US dollar, lower US Treasury yields and an improved domestic manufacturing PMI. The bigger move was against the Aussie, with NZD/AUD gaining around 1.3% to 0.8138, as softer Australian employment data saw markets pare back RBA tightening expectations. Interestingly, the speculative community, as reflected in CFTC non-commercial futures positioning data, indicates the market is at an all-time short in AUD. Whilst this may seem strange from an NZD/AUD perspective given the broader weakness, it does highlight how fast money can move when a perceived monetary policy cycle, i.e. the RBA’s, is reaching its terminal point. From a risk/reward perspective, extreme positioning is an important factor to monitor for a potential unwind. Should the market get any sniff of renewed RBA hawkishness, watch for a quick and crowded exit for the door. In this case, the downside for NZD/AUD would be exposed once more. Technically, NZD/USD faces short-term reversal levels at 0.5660, 0.5727 and 0.5775, while NZD/AUD has resistance at 0.8150, 0.8195 and 0.8240. Despite the latter's bounce, the broader downside picture remains intact while below 0.8390.
Attention now turns firmly to Thursday’s NZ CPI, with the RBNZ’s 28 October decision still “wide open”, according to comments from the RBNZ’s Paul Conway last week. With OIS pricing implying around an 80% chance of a hike, the risk/reward for the Kiwi looks interesting. A stronger inflation print would largely validate what is already priced, while a downside surprise could see hike expectations unwound relatively quickly, particularly if it puts the RBNZ back on the more benign path outlined in its previous MPS. The election adds another layer of uncertainty, leaving the NZD exposed to potentially larger two-way moves over the coming weeks.
Offshore, UK CPI on Wednesday and US PMIs on Friday headline the global calendar, while Canadian, UK and NZ inflation releases make Tuesday through Thursday a particularly busy window for G10 FX. For the Kiwi, the global backdrop still matters: last week’s recovery was assisted by a weaker USD, meaning any renewed rise in US yields or deterioration in risk appetite could challenge the rebound. NZ CPI may provide the domestic direction, but global rates, the USD and risk sentiment will determine how far the Kiwi can run. Hamish Wilkinson – Senior Dealer, Financial Markets.
The Week's Key Events
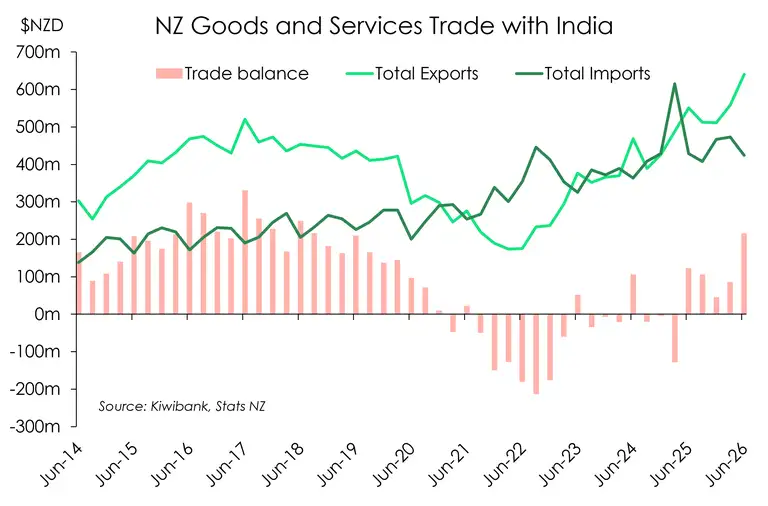
- All eyes domestically will be on New Zealand CPI data out on Thursday. That will be a headline for sure. Other data to look for this week is the NZ trade balance out later this morning for the month of September.
- China has a slew of data out today, including GDP, retail sales, industrial production, property sales, and jobless rate.
- Canada CPI is out this week also, and housing data for the US later in the week.
All content is general commentary, research and information only and isn’t financial or investment advice. This information doesn’t take into account your objectives, financial situation or needs, and its contents shouldn’t be relied on or used as a basis for entering into any products described in it. The views expressed are those of the authors and are based on information reasonably believed but not warranted to be or remain correct. Any views or information, while given in good faith, aren’t necessarily the views of Kiwibank Limited and are given with an express disclaimer of responsibility. Except where contrary to law, Kiwibank and its related entities aren’t liable for the information and no right of action shall arise or can be taken against any of the authors, Kiwibank Limited or its employees either directly or indirectly as a result of any views expressed from this information.