- The housing market continues to create winners and losers. Prices and sales data disappoint, creating ample opportunity for first home buyers. Median house prices in October are 18% below the peak, while first home buyers represent close to 30% of all house purchases in the September quarter.
- Tourism and manufacturing are serious bright spots in New Zealand’s otherwise lacklustre economy. Tourism arrivals continue to grow, while the manufacturing industry expands at a healthy pace.
- High fuel prices in October hurt spending elsewhere, with retail spending down 0.7% for the month.
The Kiwi housing market continued to drag its heels in October much like our emails did at the end of last week. Median house prices remain 18% below 2021 peaks. The national house price index (HPI) fell by 0.5% between September and October (seasonally adjusted). Compared with October 2025, the HPI is down 2.1%. The North-South divide remains stark. Southland, Otago and Canterbury are the only regions to have eked out house price growth over the past year.
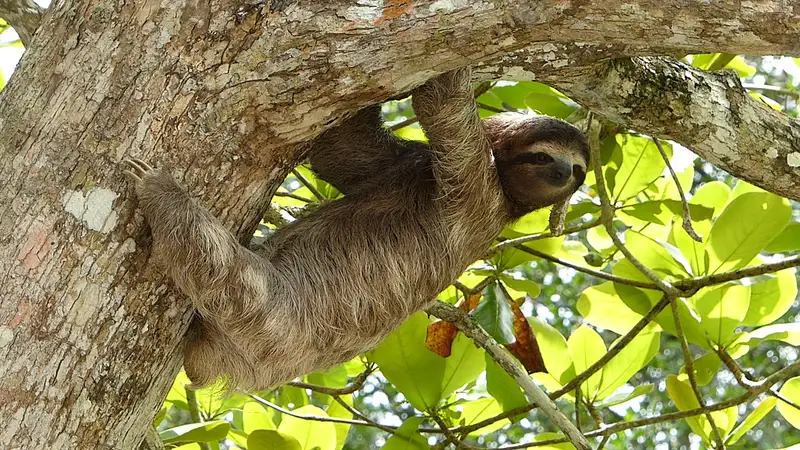
On top of that, the market is moving as fast as a sloth descending a tree (it’s slow). Median days to sell remains high at 48 days (seasonally adjusted) compared with a long-run average of 40 days. Seasonally adjusted sales in October were down nearly 9% from September, and down 24% from October 2025.
New Zealand’s housing market has been staggering sideways for four years. This isn’t great for homeowners who bought at the peak and are looking to sell. But it’s created a genuine opportunity for prospective new entrants. Earnings have a chance to catch up with house prices. Cotality data shows that first home buyers made up nearly 30% of property purchases in the September quarter. First home buyers are particularly active in the Auckland and Wellington markets, the worst hit by the correction.
The recovery will be materially slower without the often debated “wealth effect”. Falling house prices tend to crimp household and small business owner confidence. And that feeds into consumption patterns…
Retail spending continues to slide, the third consecutive monthly decline. Card spending was down across all categories except for fuel, according to Stats NZ. High fuel prices over October crowded out other spending. When petrol was more than $3.60 per litre in some parts of the country, it became a lot harder to justify spending on other stuff. Thankfully, we are seeing a gradual easing in prices at the pump, with global oil prices lower. But don’t expect any big falls any time soon. The oil price may fall, but the cost of shipping and refining has lifted… and it’s the landed price of refined product (like diesel) that counts. We suspect “slow and steady” will be the name of the game.
We are pleased to report some good news! The tourism sector is continuing to see growth in visitor arrivals. Visitor arrivals in September rose well above the pre-Covid peak in 2019. There were more overseas visitors in September 2026 than the population of Dunedin, Timaru, Invercargill, Waitaki and Gore combined... 273,000.
Australian arrival growth remains robust, with Aussie tourists making the most of the strength of their dollar compared to ours. The total overseas visitor arrivals for the year to September 2026 was 3.74 million, not bad.
Net migration is slowly picking up driven by cooling departures and growing arrivals. There is still a significant net outflow of New Zealand citizens, but net arrivals from China, India and The Philippines are strong.
The Manufacturing industry is still growing, although at a slightly slower rate compared with the month prior. Production, employment, new orders, finished stocks and deliveries are all in expansionary territory. There is clearly strong momentum in the manufacturing sector, especially in the South Island.
Financial Markets
The comments below were provided by Kiwibank traders. Trader comments may not reflect the view of the research team.
In FX – Fed fears and risk-off USD strength drive Kiwi to fresh 2026 lows
The Kiwi dollar came under steady pressure over the past week, as an initial post-election lift quickly gave way to renewed US dollar strength. NZD/USD fell around -1.9%, from 0.5632 to a 2026 low of 0.5525 on Friday, with growing expectations of further Federal Reserve tightening supporting the USD.
The Kiwi initially rallied as much as +1.6% on Monday following the New Zealand election, briefly trading around 0.5630. However, those gains proved short-lived, with broader USD strength taking over as the week progressed. The US dollar was seen as a haven across the week as equity markets soured and the risk-off tone extended into the end of the week. Expectations of a possible December Fed rate hike increased after Governor Christopher Waller indicated policymakers remained prepared to raise rates further if required.
NZD/AUD was considerably more settled, trading within a narrow 0.8125–0.8163 range and edging around +0.3% higher. Similar macro headwinds affected both currencies, although weaker risk sentiment and AI-related concerns weighed somewhat more on the AUD. Rate differentials favour the Kiwi over the Aussie for now, with the RBA appearing to be near the end of their tightening cycle while the RBNZ appear to be somewhat hesitant to tighten further. The December MPS is priced at an 88% probability of a hike from the RBNZ, but the path into 2027 is less clear. While the NZDAUD cross may continue towards the 0.8200 level, there is some resistance in the current range. Mieneke Perniskie – Senior Dealer, Financial Markets.
The Week's Key Events
- There is no shortage of data out in the week ahead. Locally, the Performance of Services Index (PSI), select price indexes, producer price indexes (PPI) and trade data are of note. Reserve Bank Governor Breman and Chief Economist Conway will be giving speeches on the New Zealand economy, the contents of which will be closely watched.
- A slew of Chinese data including for housing, retail and industrial production is also landing this week.
- Australia will see labour market data, while Japan will have GDP and trade data, the US gets retail sales, and CPI data is landing for Canada, the UK and the EU.
All content is general commentary, research and information only and isn’t financial or investment advice. This information doesn’t take into account your objectives, financial situation or needs, and its contents shouldn’t be relied on or used as a basis for entering into any products described in it. The views expressed are those of the authors and are based on information reasonably believed but not warranted to be or remain correct. Any views or information, while given in good faith, aren’t necessarily the views of Kiwibank Limited and are given with an express disclaimer of responsibility. Except where contrary to law, Kiwibank and its related entities aren’t liable for the information and no right of action shall arise or can be taken against any of the authors, Kiwibank Limited or its employees either directly or indirectly as a result of any views expressed from this information.