There is typically an inverse relationship between the VIX and the S&P500. A movement up in one is usually associated with a move down in the other. This week’s chart captures that dynamic, with a massive drop in the S&P500 and simultaneously a massive spike in the VIX observed at the end of last week.
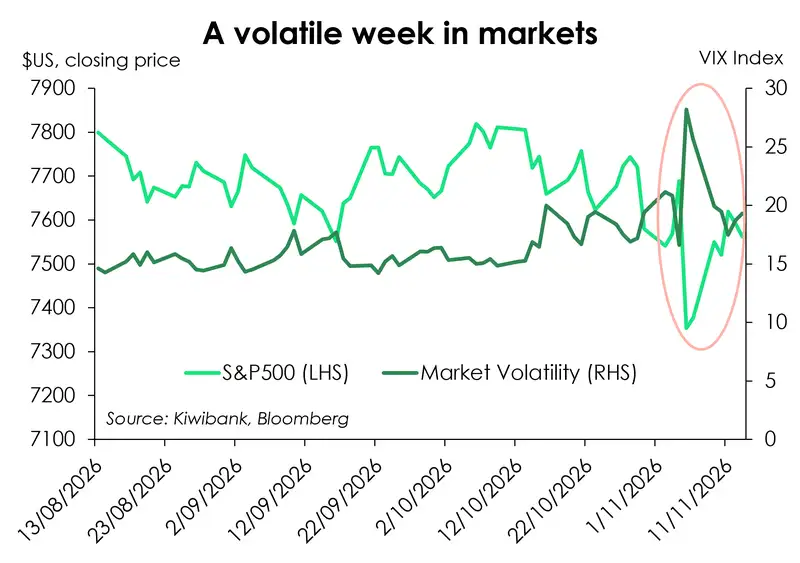
The last few weeks have been a wild ride in terms of sharp market moves. First, US and Iran talks eased global fears that the war would continue indefinitely. Next, the US-midterm election saw the Democrats “blue wave” sweep the nation and drove optimism of a more diplomatic approach to the Middle East situation. That was until everyone thought of the consequences that come with a Democrat-led House and Senate. The fear of regulation being imposed on AI tech firms led to some investors pulling out of AI.
The move meant that tech-heavy index funds all saw 5% or larger drops within a day. Trillions of dollars were wiped out of US equities. The NASDAQ’s erasure of more than $2 trillion USD in market value on 6 November was the largest single-day loss by market value on record for that index.
The move was dominated by a fall in semiconductor or ‘chip’ stocks. NVIDIA was particularly impacted amidst news that its now ousted CEO, Jensen Huang, had extramarital affairs with an alleged Chinese spy and other individuals. It sounds like something out of a movie.
The sell-off could have caused a cascade even lower. But some investors saw the drop in price as an opportunity, a “sale” of sorts. As investors bought the dip, index funds recovered just as sharply as they had fallen. These swings in prices were enough to make many heads spin.
European equities on the other hand, which are less AI exposed to their American counterparts, actually had a pretty good run amidst the chaos in US markets. The Stoxx 600 (a broad measure of the European equities market) is comprised of roughly 8% technology stocks, compared with the roughly 35% of the S&P500. It’s easy to see why European equities were able to shrug off the chips and dip debacle across the other side of the Atlantic. The Stoxx 600 rallied 2.4% last week, its best week since July.
All content is general commentary, research and information only and isn’t financial or investment advice. This information doesn’t take into account your objectives, financial situation or needs, and its contents shouldn’t be relied on or used as a basis for entering into any products described in it. The views expressed are those of the authors and are based on information reasonably believed but not warranted to be or remain correct. Any views or information, while given in good faith, aren’t necessarily the views of Kiwibank Limited and are given with an express disclaimer of responsibility. Except where contrary to law, Kiwibank and its related entities aren’t liable for the information and no right of action shall arise or can be taken against any of the authors, Kiwibank Limited or its employees either directly or indirectly as a result of any views expressed from this information.